From 1 July 2026 the ATO applies a new test to a holiday home you also rent out. If the place is not mainly rented, you lose the interest, rates, insurance and repairs deductions altogether, including for the weeks it was let. What decides it is who gets the house at Christmas, Easter and school holidays.
First, who this is not about
Most people with a second place somewhere nice do not need to read past this section.
- You never rent it out. Nothing has changed. There is no income to declare and there were never any deductions. Keep the rates notices and the receipts for anything you build or fix, because they reduce the capital gain when you eventually sell.
- You never stay there, and nor do family or friends for free or cheap. Then it is an investment property, not a holiday home, and the new rule does not touch it. The usual rental rules apply.
- You rent it hard, and take a week or a few weekends in the quiet season when it is empty anyway. The ATO’s own examples say you are fine. You leave out the days you used it, as you always have, and claim the rest.
Read on if you own a place at Merimbula, Bright or on Lake Hume that is listed for rent, and any of these is true. The family has it at Christmas, Easter or the January school holidays. Friends and relatives stay at mates rates. You knock back bookings you do not like the look of. Or you moved a long term tenant out so you could use it yourselves.
What changed, and when
12 November 2025
The ATO published a draft ruling on rental properties and withdrew IT 2167, the 1985 ruling every holiday home claim had been built on since.
20 May 2026
The ruling was finalised as TR 2026/1, with two compliance guidelines beside it: PCG 2026/2 on how to split the costs, and PCG 2026/3 on which holiday homes the ATO will look at first.
1 July 2026
The ATO has said it will not chase costs from before this date. The year that started on 1 July 2026 is the first one judged the new way.
Christmas 2026
The first peak period that counts. The test looks at the whole income year, so what you do with the house this summer is already part of your 2027 return.
The 2026 return we are preparing for you now sits on the old side of that line. Nothing about it needs to be redone.
The old test counted days. The new one does not
Until now a rented holiday house was worked out on a calendar. Rented or genuinely available 300 days, yours for 65, so you claimed 300 out of 365 of the interest, rates and insurance. The only fight was whether the 300 days were genuinely available. Our 2023 note on what the ATO checks was written for that world.
The new ruling adds a step in front of the calendar. First, is the place a holiday home at all? It is, if you, your family or your friends use it for holidays, free or at a discount, even occasionally. The ATO’s example is a seaside unit the owner stays in for one or two nights a year in the off season, and that counts.
If it is a holiday home, the second question decides everything: at all times during the year, was it used or held mainly to earn rent? If the answer is no, every cost of owning the place is switched off. Not reduced. Off.
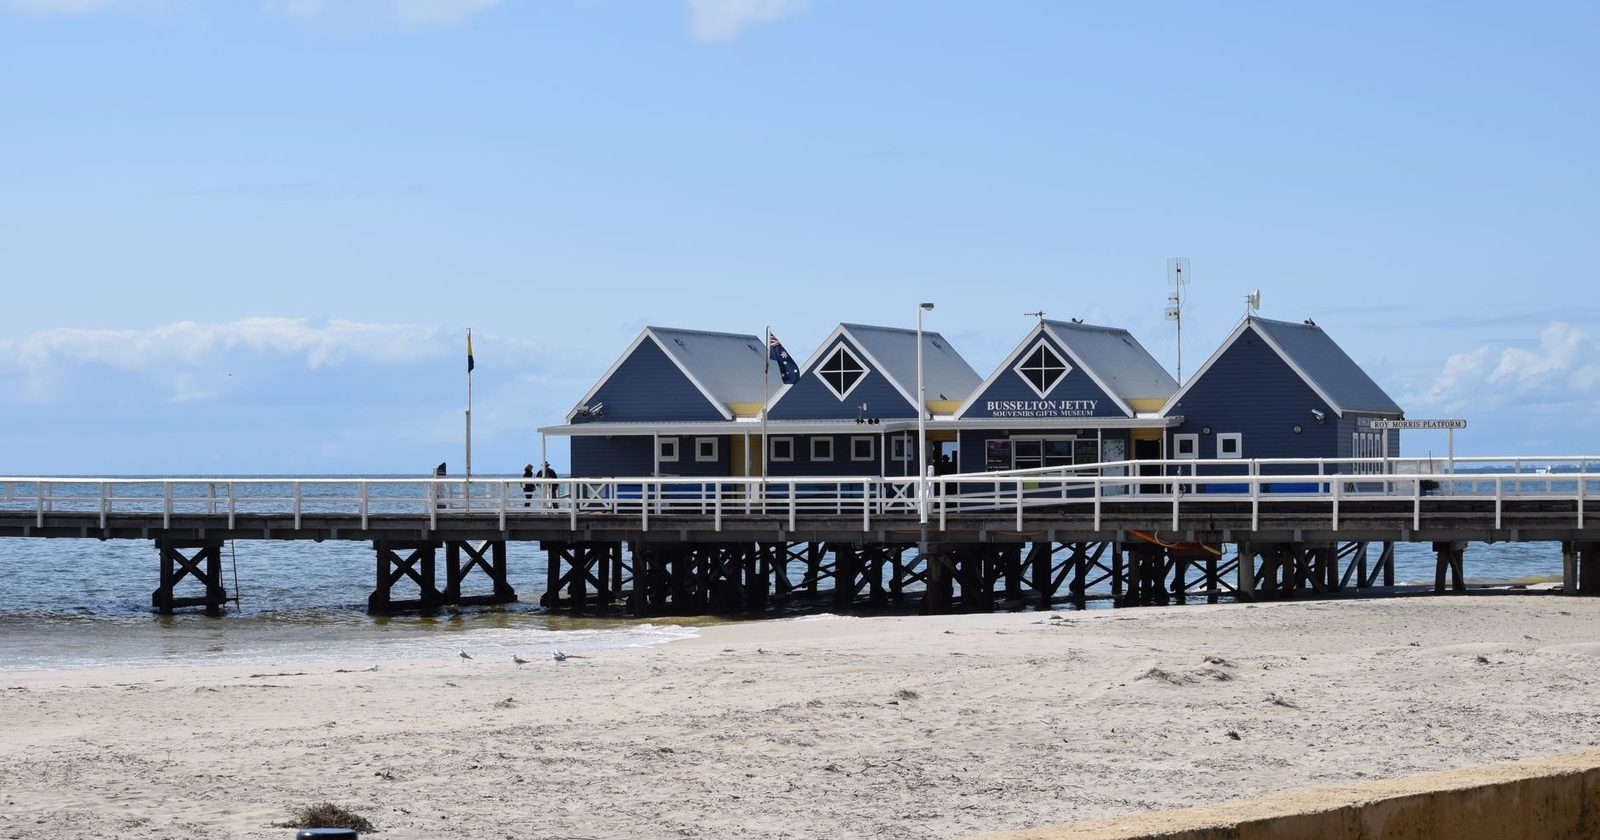
A house listed 300 days a year and blocked out for Christmas, Easter and the January school holidays can fail it. The ATO’s own example is a Busselton beach house, advertised all year through an agent, rented about ten weeks, and held back every peak period whether the family turned up or not. Result: every ownership cost denied.
| Cost | Under the new rule |
|---|---|
| Loan interest | Denied in full, including for the weeks it was rented |
| Council and water rates, land tax, body corporate | Denied in full |
| Building insurance | Denied in full |
| Repairs and maintenance | Denied in full |
| Capital works and depreciation | Denied in full |
| Platform fees, agent commission, advertising | Still deductible, as they relate only to the letting |
| Cleaning and laundry between guests | Still deductible |
| The rent itself | Still fully taxable |
That last row is the sting. The income stays in, the costs come out. A house that used to produce a small tax loss each year produces a taxable profit instead, on the same bookings.
The three groups the ATO has sorted owners into
The ATO sorts rented holiday homes into green, amber and red. These are its own examples, with the names kept.
Green. The ATO will not look. Eric has a Gold Coast unit in a managed rental pool with high occupancy. He blocks out four weeks a year for his own holiday, in the low season, and stays the odd night when it happens to be empty. Ricky has a Busselton beach house that is full all summer; he takes one week off peak and the odd short stay when nobody has booked, and gives way if a booking comes in. Both keep their deductions and leave out the days they used it.
Amber. The ATO may look. Ling has a chalet at Thredbo. Through the four month ski season she is there a few days a fortnight and blocks it out to ski. When she is not there it is fully booked. In the off season it gets the odd weekend. The ATO’s comment is that she has the house in the exact weeks it earns the most, and if she wants to be in the green that has to change. Ryan and Tom, who use their Melbourne apartment for the tennis, the Grand Prix and the football and rent it the rest of the time, get the same comment.
Red. The ATO will look, as a priority. Josh’s Busselton house, above. Andy’s house on a Hunter Valley golf course, blocked every Sunday for his own round, four night minimum stay, and guests warned the phone reception is poor. Shane and Carmen, who retired, moved their long term tenants out of the Glenelg unit and put it on the short stay sites so they could use it themselves, rarely answer enquiries, and cancel a booking if it clashes with their plans. All three lose the lot.
If you own a chalet at Falls Creek or Hotham and ski from it through the season, read Ling’s example twice. The ATO wrote it for you.
Family and mates rates
Rent from your brother, your daughter or your fishing mate is still income, however little it is. If it is below the going rate, your deductions on the place are capped at the rent you received from them, so the stay can never produce a loss. That has been the ATO’s position for years.
What is new is that under the ruling, a relative or friend staying free or cheap counts as your holiday use. It makes the house a holiday home, and it weighs against you on the “mainly rented” question, especially if it happens at Christmas. A sister in law who gets the place every January at a hundred dollars a night is, to the ATO, no different from you being there.
Family who pay the market rate, with evidence of what the market rate was when you set it, are ordinary tenants and none of this applies to them.
If you want to keep the deductions, this has to be true
There is no form to fill in. The ATO reads the booking calendar. To be in the green, all of this has to be true through the year:
- The peak periods are open to paying guests. Christmas, Easter and school holidays are when the house earns, and they are the first thing the ATO looks at.
- An agent or the platform handles enquiries and you accept the bookings that come. Knocking back enquiries without a reason is enough on its own to put you in the red.
- The rent is in line with similar places nearby, and there are no odd conditions. A four night minimum, no children, no pets and “bring your own linen” together read as a house you do not really want to let.
- Your own use is in the off season, when it was empty anyway, and it is short. A week, a few weekends, the odd night.
- Nothing is locked away from guests. The boat, the jet ski and the wine collection kept off limits to guests are in the ATO’s red zone example by name.
- Family and friends pay the market rate, or you accept that their stay is counted as yours.
Two things that will not work. The ruling has its own rule against dressing it up, so leasing it to your own family trust, or any paper arrangement that makes the house look rented, does not move it into the green. And a seasonal pattern, rented in winter and yours in summer, is never treated as a change of use. Only a definite and sustained change counts, such as moving interstate and handing the place to an agent full time, and from that point the deductions come back.
If you read that list and thought “but then it is not our holiday house any more”, that is the honest answer the ruling is forcing. Plenty of owners will decide the family comes first, claim nothing on the ownership costs, keep the receipts for the cost base, and sleep fine. The one thing that no longer works is doing both.
Costs you cannot claim are not wasted
If the house fails the test, the interest, rates and repairs you can no longer deduct can still be added to the property’s cost base, which reduces the capital gain when you sell. So keep every rates notice and every interest statement even in the years you claim nothing. Throwing them out because “we can’t claim it anyway” is the expensive mistake.
How that gain is taxed also changes from 1 July 2027. We have written it up in what the 2027 capital gains tax changes mean for you. The same legislation restricts negative gearing on established residential property bought after 7:30pm on 12 May 2026, which matters if you are about to buy another.
The records that settle it
The booking platforms have reported every payment to the ATO since 1 July 2023, so the income side is already known. What you need to be able to show is the use side.
- The full year’s booking calendar from the platform or the agent, including the blocked out dates and who blocked them.
- The platform’s annual earnings statement, which should agree with what we put in the return.
- Evidence of the market rate when you set the price: comparable listings, or a note from the agent.
- A simple diary of who stayed and when, including you, family and friends, and what they paid.
- Your written instructions to the agent, if there are any about holding dates back.
What we will do
- Go through your last twelve months of bookings and tell you, in writing, which of the three groups the house sits in today.
- Finish your 2026 return on the old basis, which is still the right basis for that year.
- Show you what the 2027 return looks like both ways, with your numbers: keep the deductions and open up the peak periods, or keep the house for the family and claim only the letting costs.
- If you choose to keep the deductions, write out exactly what changes before Christmas and what to tell the agent.
- If you choose the family, set up the cost base file so none of those costs are lost at sale time.
Our rental property page covers the rest of what we do for property owners. For a holiday house the first job is the one above, and it is a one meeting job.
Own a rented holiday house? Let us check it before summer
Bring the booking calendar, or just tell us how the place gets used. We will tell you which group you are in and what the 2027 return will look like.
Written by the tax team at Business Edge Advisors, Registered Tax Agent 20651000. Sources: Taxation Ruling TR 2026/1, Practical Compliance Guidelines PCG 2026/2 and PCG 2026/3, all issued 20 May 2026, and the compendium TR 2026/1EC, read directly on the ATO legal database on 20 October 2026. The transitional approach is paragraph 138 of the ruling. The negative gearing and CGT discount changes are in the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, which received Royal Assent on 26 June 2026. General information, not advice about your circumstances. Talk to us before acting on any of it.