Two things changed for teachers this year, and one of them settles the home office argument for good. The rest of this is teacher tax deductions claim by claim, so go straight to the one you were about to get wrong.
Jump straight to
Every staffroom has someone who claims everything. The laptop, the handbag, the coffee, the trip to Bali that had a conference in it somewhere. They have never been audited, so the story keeps getting told, and every July somebody believes it.
This is not that. It is what actually holds up, written for someone who wants the deduction they are entitled to and does not want a please explain in eighteen months.
Check this first. If the school paid you back for it, there is no deduction, however much it cost you. That is the single most common error on a teacher’s return, and it is worth checking before you add up anything below.
What changed
The teacher ruling was withdrawn
TR 95/14 listed what a teacher could claim for thirty years. It was withdrawn from 19 June 2025 and nothing occupation specific replaced it.
The home office question was settled
The Full Federal Court decided in April 2026 that an employee cannot claim rent or mortgage interest for a home office. Not even a dedicated one.
Claim by claim
Teaching aids and classroom supplies
- What you can claim
- Things you buy to do the teaching and the school does not pay you back for. Readers, art materials, laminating, prizes for the reward chart, a set of counters, the storage tubs they live in. If it is used in the classroom and it came out of your pocket, it counts.
- Where it goes wrong
- Two places. The first is reimbursement: if the school gave you the money back, there is no deduction, and this is the single most common error in education. The second is the word “aid” doing too much work. A bookshelf for your lounge room is not a teaching aid because you keep readers on it.
- How to make it stick
- Keep the receipt and write on it what it was for and which class. Anything over $300 that lasts more than a year gets written off over its life rather than all at once, so keep those separate.
Working from home
- What you can claim
- 70 cents for every hour you actually worked at home, under the ATO’s fixed rate. That one rate covers electricity and gas, internet and data, your mobile and home phone, stationery and computer consumables. You can still separately claim the decline in value of a desk, chair or computer.
- Where it goes wrong
- Claiming the hours, then claiming the phone and internet again on top. They are already inside the 70 cents. Doing both is the clearest double dip on a teacher’s return and it is easy for the ATO to see. The other one is the record. You need the actual hours for the whole year, written down as you go. A four week sample multiplied out is specifically not accepted, and “about ten hours a week” is not a record.
- How to make it stick
- A diary, a spreadsheet, or the calendar on your phone. Whatever you will actually keep. And be honest about what counts: marking and planning at the kitchen table is working from home. Answering a parent email at nine at night on your phone is not a shift.
Car and travel
- What you can claim
- Driving between two workplaces on the same day. Relief teaching at a second school, taking a class to the pool, going to the district office and back. Either 88 cents a kilometre up to 5,000 kilometres, or the logbook method if you drive a lot.
- Where it goes wrong
- Home to school is private travel and always has been, no matter how much gear is in the boot or how early you start. Carrying bulky equipment is a narrow exception and a laptop bag full of marking is not bulky. In 2026 the Full Federal Court also confirmed that driving from your home office to your workplace is not deductible either, so setting up a study does not convert the commute.
- How to make it stick
- A note of the date, the two places and the kilometres. Even under the cents per kilometre method you have to be able to show how you worked the number out.
Self-education
- What you can claim
- Study that maintains or improves the skills you use in the job you have now. Course fees, textbooks, stationery, the travel to get there. A primary teacher doing a literacy intervention qualification is squarely in.
- Where it goes wrong
- Study that gets you a different job, or a better one you do not have yet. That is the line, and it catches more teachers than any other rule. A tribunal denied a maths and science teacher the accounting and marketing subjects in a postgraduate degree, because neither those subjects nor the course as a whole improved what he did in the classroom. General self-improvement and personal development courses usually fail for the same reason.
- How to make it stick
- Be able to say, in one sentence, which part of your current duties the course improves. If the honest answer is that it helps you get promoted or move out of the classroom, it is not deductible, however good an idea it is.
Clothing and laundry
- What you can claim
- A uniform with the school logo on it. Protective gear that the job genuinely needs: a sun hat and sunscreen for playground duty, an apron for art, closed shoes and safety glasses for a workshop or a science prep room. Laundry of those items, at the ATO’s rates.
- Where it goes wrong
- Ordinary clothes. Conventional clothing is private even when your employer tells you to wear it, even if you only ever wear it at work, and even if there is a dress code in the staff handbook. The plain navy polo with no logo is not deductible. Neither is the outfit for parent teacher night.
- How to make it stick
- Ask whether the item is protective or branded. If it is neither, it is clothing, and clothing is private.
Phone and internet
- What you can claim
- The work share of your bill, if you are not already claiming the 70 cents an hour working from home rate. Work out the percentage over a representative four week period and apply it to the year.
- Where it goes wrong
- Claiming it twice, as above. Or claiming a round number with nothing behind it. Fifty per cent is a very popular figure and almost nobody can show how they got to it.
- How to make it stick
- Pick one method and use it. If you are claiming hours at home, your phone and internet are done and you do not touch them again.
Excursions, camps and school trips
- What you can claim
- Your own costs of going, where you are there to supervise and teach. Bus fare, entry, meals and accommodation on a camp you are running.
- Where it goes wrong
- Paying for a student. A kind thing to do and not deductible. Also the trip where you supervised for two days and stayed on for five, which becomes a holiday with a work component and has to be split.
- How to make it stick
- Keep the itinerary alongside the receipts. It is the document that shows which days were work.
Union fees, registration and subscriptions
- What you can claim
- Union fees, professional association memberships, your teacher registration, and journals or professional publications you actually use.
- Where it goes wrong
- Very little. This is the most reliable claim on a teacher’s return, and it is often the one people forget because it comes out by direct debit and never crosses their mind.
- How to make it stick
- The union sends an annual statement, so this is the one claim you do not have to hunt for.
Gifts for students, and buying their things
- What you can claim
- Nothing, as a rule.
- Where it goes wrong
- This is the one teachers hate, because it is the most generous thing they do. Buying lunch for the kid who never has any, covering an excursion for a family who cannot, the end of year presents. The ATO treats all of it as private, because the reason you did it was personal rather than to earn your income. Classroom materials the whole class uses are different and are covered above.
- How to make it stick
- It does not. If the school has a hardship fund, contributions to that may be deductible as a donation if the fund is a deductible gift recipient, which is worth asking about.
Laptops, tablets and the rest of the tech
- What you can claim
- The work share. Under $300 and mostly for work, claim it outright. Over $300, you claim the decline in value over its effective life, again only for the work share.
- Where it goes wrong
- Claiming the whole laptop. It is the second most common education error after reimbursements. The family uses it, the kids do homework on it, you watch things on it. A hundred per cent work use on a home laptop is a claim you will struggle to support.
- How to make it stick
- Keep a four week diary of use, split it honestly, and claim that percentage. Seventy per cent that you can explain is worth more than a hundred per cent you cannot.
First aid, working with children and other clearances
- What you can claim
- A first aid course where you are the designated first aid officer for the school. Renewals of registration you need to keep working.
- Where it goes wrong
- The initial cost of getting a qualification or clearance you needed before you could start the job is generally not deductible, because it was incurred to get the position rather than in doing it. Renewing one you already hold is treated differently.
- How to make it stick
- Know which one you are looking at, and check the wording on your school’s first aid roster if you are claiming the course.
The ones that get knocked back
These come up every year. None of them are close calls.
| The claim | Why it fails |
|---|---|
| Driving to school | Private travel, always. Getting to work is not doing work. |
| Rent or mortgage interest for a study | Settled by the Full Federal Court in 2026. Not deductible for an employee even with a dedicated room. |
| The whole laptop | The household uses it. Only the work share is deductible. |
| Everyday clothes and shoes | Conventional clothing is private even when the school requires it. |
| Gifts and lunches for students | Generous, and personal. No connection to earning your income. |
| Anything the school paid you back for | You are not out of pocket, so there is nothing to deduct. |
| Gym, yoga and flu shots | Private, even where the job is physical or the school encourages it. |
| A degree that changes your career | Deductible study improves the job you have, not the one you want. |
| Hours at home, plus phone and internet | The 70 cents an hour rate already includes both. |
Who actually got caught
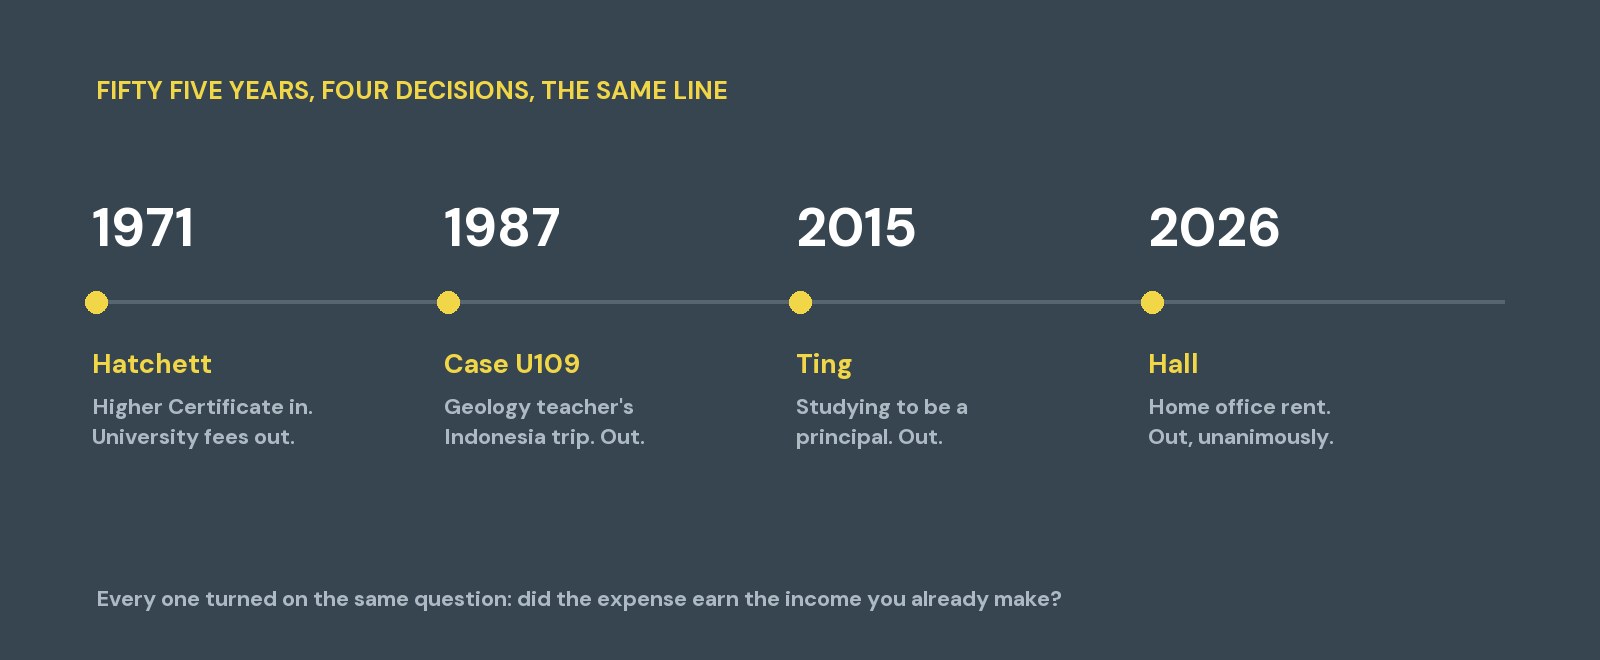
These are real decisions, argued and lost. The useful thing about them is the span: fifty five years between the first and the last, and the line has not moved.
The teacher who took the class to Indonesia
- What happened
- A science teacher who specialised in geology and ran the school science department took a 17 day trip to Indonesia with a natural history society. He visited volcanoes and geological sites, attended a geological congress, took slides throughout and recorded a taped commentary he then used in his teaching.
- What the Tribunal said
- Not deductible. The trip was recreational in character, and the Tribunal noted that some people are fortunate enough to find personal and recreational satisfaction in their own field. Genuinely using the material in class afterwards did not save it.
- The lesson
- Doing something you would have enjoyed anyway, and then teaching about it, is not the same as incurring an expense to earn your income. This is the one that catches the overseas trip with a conference bolted on.
Case U109 87 ATC 657, Administrative Appeals Tribunal.
The teacher studying to become a principal
- What happened
- A high school teacher enrolled in a postgraduate management course and completed six subjects, expecting it would help him become a leading teacher and eventually a principal. He claimed the lot.
- What the Tribunal said
- The financial accounting and marketing subjects were denied. The Deputy President held that a classroom teacher’s income-earning activities stand in contradistinction to a leading teacher’s, which is a management role. Promotion of that kind is not more money for the same work, it is a new set of activities, so the study was getting him a different job rather than improving the one he had.
- The lesson
- The most expensive misunderstanding in teacher self-education. Career progression feels like it must be work related. For tax it is the opposite of the test.
Ting and Commissioner of Taxation [2015] AATA 166.
The teacher whose university fees were too remote
- What happened
- A Western Australian teacher claimed two things: the cost of submitting theses for a Teacher’s Higher Certificate, and university fees for Arts subjects. The High Court split them.
- What the Court said
- The Higher Certificate was deductible, because it directly produced higher pay in the job he already had. The university fees were not. The connection to his income was, in the Court’s word, problematical, and the Court noted he had not passed the examinations.
- The lesson
- This is the 1971 case the whole area still runs on, and it is why “my employer encouraged it” is not the test. In a later case a teacher was partly reimbursed by the employer and still lost.
FCT v Hatchett (1971) 125 CLR 494; 71 ATC 4184, High Court of Australia.
The employee who had to work from home and still could not claim the rent
- What happened
- A presenter was required to work from home during lockdowns. He used the second bedroom of a rented flat exclusively for work, for three quarters of his job, and claimed the share of the rent for that room.
- What the Court said
- No, unanimously. Rent, mortgage interest, rates and insurance are occupancy expenses, and for an employee they keep their private character however the room is used. Being compelled to work at home did not change it. Nor did using the room only for work. The Court also held that driving from that home office to the employer’s premises was not deductible, because it is travel to work rather than in the course of it.
- The lesson
- The one that answers the staffroom question directly. Your 70 cents an hour running costs are available. The rent is not, a dedicated room unlocks nothing extra, and setting up a study does not make the drive to school deductible.
Commissioner of Taxation v Hall [2026] FCAFC 43, Full Federal Court, April 2026.
What to do between now and June
Start the hours log
If you work at home at all. It has to run the whole year and it cannot be reconstructed later.
Photograph receipts as you go
Write what it was for on the photo. Faded thermal paper in August is worth nothing.
Ask what the school reimburses
Before you claim it. Most teachers are not certain, and it is the error that comes up most.
Add it up once in May
With last year’s return beside you. Five minutes tells you whether you are claiming what you are actually entitled to.
Questions we get asked
Everyone at my school claims $300 with no receipts. Is that a thing?
Sort of, and it is widely misunderstood. If your total work expenses are $300 or less you do not have to keep written evidence, but you still have to have spent the money and be able to explain how you worked out the claim. It is not a free $300, and inventing one is exactly the claim the ATO’s data matching is built to find.
Can I claim my Master of Education?
It depends entirely on what it does for the job you hold now. A course that deepens what you already teach is usually deductible. One that is really about moving into leadership, or into a different field, usually is not. Ask what part of your current duties it improves, and be honest about the answer.
The school gives me a desk, so can I still claim working from home?
Yes, for the hours you genuinely work at home, at 70 cents an hour. Having an office at school does not disqualify the running costs. What it will not get you is rent, mortgage interest or rates, and after the 2026 Full Federal Court decision that is true whether or not you have a desk at school.
What happens if I have claimed things I should not have?
Amend it. A voluntary amendment is treated very differently from something found in a review, and the penalty position is usually far better. It is a dull conversation rather than a frightening one.
Not sure about something you bought?
Bring the receipt and tell us what you use it for. That is almost always enough for us to work out what belongs in the return and what does not, and you will be told plainly either way rather than left guessing.
We do individual returns for teachers and school staff across Albury, Wodonga and the border. If you would rather see how it works first, the tax return page covers what to bring and what it costs.
Related reading
- Claiming home office expenses as an employee, which goes deeper on the hours, the records and what the 70 cents covers.
- Truck driver tax deductions, the same claim by claim treatment for a job with very different rules.